Every Drop Counts Twice: Untangling the IRS Mess Behind Crypto Plinko Winnings
Photo: edwinchuen, CC BY 2.0, via Wikimedia Commons
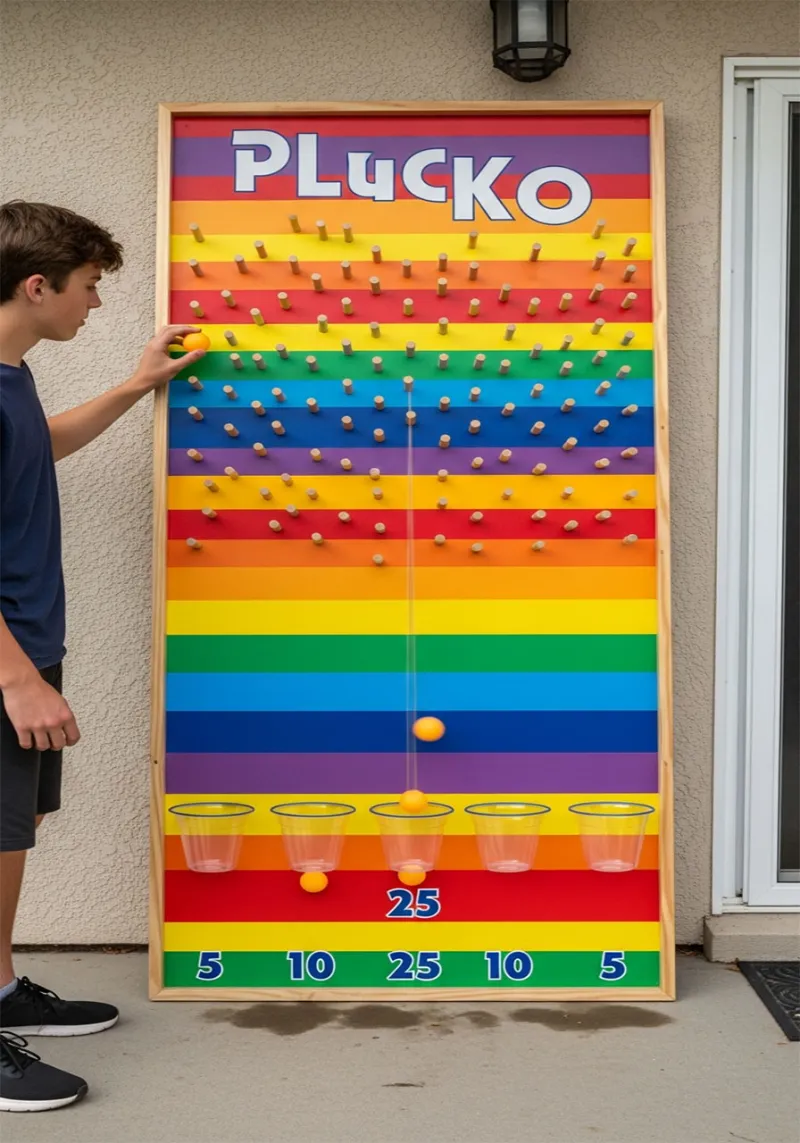
Here's the thing nobody mentions when you're watching that ball bounce toward a 1,000x pocket: the IRS doesn't care how fun the game was. It cares about the transactions.
And if you're playing Plinko at a crypto casino from the US, you've probably generated more taxable events this year than a day trader.
The Part That Surprises Everyone
Ask most players about crypto taxes and they'll say something like, "I only owe when I cash out to my bank." That's wrong, and it's the mistake that gets people in trouble.
Under IRS guidance, cryptocurrency is treated as property. That means disposing of it — selling, trading, or using it to buy something — is a taxable event. And yes, converting USDT to BTC to load your casino wallet counts. So does moving between coins mid-session. So does cashing out.
"The most common misconception I see with gamblers is that only the final withdrawal matters," says Dana Reyes (name changed at her request), a CPA in Texas who specializes in digital asset reporting. "In reality, every swap along the way creates a gain or loss calculation. If you converted Ethereum to USDT in February and Ethereum had appreciated since you bought it, that's a reportable gain — even if you lost every bet afterward."
Read that again. You can owe tax on a winning trade that funded a losing session.
What Actually Counts as a Taxable Event
Let's simplify. In the Plinko context, these usually trigger reporting obligations:
- Buying crypto with USD — not taxable by itself, but it establishes your cost basis
- Swapping one coin for another — taxable, full stop
- Depositing to a casino — depends on the structure, but any conversion involved likely is
- Cashing out winnings — taxable on any appreciation between acquisition and sale
- Using crypto directly to bet — this is where it gets genuinely murky, and where platforms differ wildly
Notice what's missing from that list: "winning at Plinko." Gambling winnings are taxable as income regardless of the payment method, but proving what you won versus what you merely shuffled between wallets is the real challenge.
The Record-Keeping Nightmare
Traditional casino gamblers get a W-2G for big wins. Crypto Plinko players get... nothing. Offshore platforms don't issue US tax forms. Some don't even ask your name.
That means the burden of reconstruction falls entirely on you. If you played 200 drops a night at 0.0001 BTC each, that's thousands of micro-transactions to account for — each with its own cost basis question.
"I had a client who came to me in March with a spreadsheet that said 'casino stuff, maybe $4k?'" Reyes told us. "Reconstructing a year of on-chain activity took weeks. It's doable, but it's not cheap, and it's a lot harder than keeping records as you go."
Tools That Do the Heavy Lifting
The good news: you don't have to do this by hand. A wave of crypto tax software can plug into your wallet addresses and exchange accounts and rebuild your transaction history automatically.
Koinly, CoinTracker, and TokenTax are the big three most US players land on. Connect a wallet or paste an address, and the software ingests the on-chain history, categorizes transactions, and flags likely gambling activity. They'll generate IRS Form 8949 and Schedule D outputs, and most handle the crypto-specific cost-basis methods (FIFO, HIFO, and so on) automatically.
A few practical notes from our testing:
- Import every wallet you used. Missing even one address creates gaps the software can't reconcile.
- Tag gambling transactions manually if needed. Most tools can't reliably distinguish a casino deposit from a transfer to a friend. Labeling as you go saves a brutal March.
- Watch for missing cost basis. If you bought coins on a platform that's since gone dark — and in crypto, they do — the software may assume a zero basis, which inflates your taxable gains. Fix this before filing.
- Export everything. Keep the raw CSVs. If the IRS ever asks questions, "the software said so" isn't a defense; your underlying records are.
For high-volume players, Reyes suggests a simpler habit going forward: "Screenshot your session summaries and monthly balances. It's not a substitute for proper records, but it gives a professional something to work with if the chain data doesn't tell the whole story."
Losses, Deductions, and the Fine Print
Can you write off Plinko losses? Sort of. Gambling losses are deductible — but only up to the amount of gambling winnings you report, and only if you itemize deductions. Casual bettors taking the standard deduction often get no benefit from their losses at all, while winnings remain fully taxable. It's an asymmetry worth knowing about before you chase anything.
Also worth noting: the IRS has been increasing enforcement attention on digital assets, and the tax form now asks directly whether you've received or disposed of digital assets during the year. Answering that question dishonestly is a federal problem, not a state one.
The Bottom Line
Nobody gets into Plinko because they love record-keeping. But the gap between how crypto gambling feels — instant, frictionless, anonymous-ish — and how the IRS treats it — a chain of property dispositions requiring documentation — is exactly where players get burned.
Set up a tracking tool now, tag your transactions monthly, and talk to a CPA who actually understands digital assets if your volume is meaningful. April 15 comes for everyone, including the guy who hit a 1,000x drop in January and didn't save a single record.
This article is general information, not tax advice. Consult a qualified tax professional about your specific situation.